
Buyer Guide
hello!
Buying a home is a big decision, and I want you to feel confident at every step. This guide walks you through buying in North Carolina, from pre-approval to the closing table. Along the way you'll find worksheets to help you get clear on what you want and checklists to keep you on track. Save the link, and text me anytime a question comes up. No question is too small.
I'm Lex Fowler, a REALTOR® with The Foundry Group at Compass, a military spouse, and a Southern Pines transplant whose favorite part of this work is helping people find the place that feels like home.
Inside this guide
Who's on your side
The Value of a Buyer's Agent
A listing agent represents the seller. As your buyer's agent, I represent only you, from our first showing to closing day.
The process
The Home Buying Process at a Glance
From pre-approval to the closing table, here's roughly how the timeline plays out.
Preparation. Assess your finances and get pre-approved for a mortgage so you know your budget.3–9 months out
Search & offer. Tour homes that fit your budget, find the one and write a strong NC offer together.45–60 days out
Under contract. Complete inspections during your Due Diligence Period, negotiate repairs and finalize your loan.30–45 days out
Closing prep. Review your Closing Disclosure, confirm moving plans and verify wiring instructions with your attorney.1–2 weeks out
Closing day. Sign with your closing attorney. Once the deed is recorded, the keys are yours!Closing day
After closing. Set up utilities, update your address and keep your closing documents somewhere safe.1–7 days after
Let's talk finances
The Mortgage Process
Your first step is getting pre-approved with a local lender so you know exactly what you can afford. I recommend talking with a few lenders to find the right fit, and I'm happy to share recommendations.
- What type of loan do you recommend for me, and why?
- What are my interest rate, APR and estimated monthly payment?
- Can I lock in my rate? For how long, and are there fees?
- Do I qualify for down payment assistance, like NC Housing Finance Agency programs?
- Can you order my appraisal and start underwriting within my Due Diligence Period?
- What will my closing costs be? Are they part of my loan, or paid at closing?
- Will I pay mortgage insurance or a VA funding fee?
- Pre-approvals are usually valid for 30–90 days, so time the official letter for when you're ready to shop
- First-time buyer? Ask about NC Housing Finance Agency programs
- Relocating on PCS orders? Tell your lender early
Get clear on non-negotiables
Consider Wants & Needs
Before we start touring, make two lists. Needs are your non-negotiables. Wants are things you'd love to have but could add or change later. Remember, you can't change the lot, the location or the price you paid.
- Enough bedrooms for your family
- A first-floor primary bedroom
- Close to work or school
- A yard for kids or pets
- A fenced-in backyard
- Specific flooring
- A walk-in shower or double vanity
- Write down everything you'd like in your ideal home. Don't hold back.
- Rank each item from 1 (unnecessary) to 10 (absolutely crucial).
- Use your rankings to sort each one into a want or a need.
Now the fun begins
The Home Search Process
With your wants vs. needs list in hand, we'll share listings through your Compass One dashboard, where you can save favorites and send me notes, then narrow down which homes to see in person.
Use filters, but don't go crazy. Search too narrowly and you'll only have a handful of homes to view.
Take a virtual walk. Online photos can be deceiving, so check Google Street View for a feel for the house and the street around it.
Collaborate in your dashboard. Favorite and comment on homes, track new listings and price changes, see Compass-exclusive listings, and request tours, all in Compass One.
Block time to tour. Set aside time for the homes on your shortlist. Not in town yet? I can tour homes for you by video.
- What area(s) are you looking to buy in, and what do you like about them?
- How many bedrooms and bathrooms, what square footage, and one or two stories?
- What's your favorite style of home?
- What are the top five most important things in your future home?
- What's one non-negotiable?
- Do you have children? Pets?
- Anything else I should keep in mind during our search?
Get ready for the fun part
It's Time for Showings!
You're ready to get inside the homes on your shortlist and see if one of them is your soon-to-be address. Here's what to keep in mind.
- Reread your wants vs. needs list and revisit your budget before you go
- Take photos and videos to jog your memory later
- Look past decor and staging. It will soon be gone!
- Ask me for recent sales and price trends to gauge resale value
- The lot, lot size and location, since none of these can change
- Signs of structural issues: water damage, cracks in walls or ceilings, sloping floors
- The roof, siding, windows, doors and overall exterior
- Layout, room sizes, storage and flow
- Noise from roads, rail lines and flight paths. Closer to Fort Bragg, you may hear training activity.
- Exterior rating, 1–10
- Interior rating, 1–10
- Three pros and three cons
- Gut reaction: no, maybe, very interested or it's the one!
Let's make it stand out
Writing Your Offer
Found the one? In North Carolina, price is only part of the picture. Your terms matter just as much.
Include your pre-approval letter. It shows you're serious, qualified and ready to buy.
Put your best foot forward. You may only get one shot, so we'll use recent comparable sales to choose the right price to lead with.
Use your terms to stand out. A stronger Due Diligence Fee, a shorter Due Diligence Period, larger Earnest Money or a flexible closing date can all make a difference.
Plan around your current home. If you need to sell first, we'll talk through how that affects your offer.
Lean on my experience. I'll help you structure an offer that gives you every advantage.
Cue the confetti
You're Under Contract
Your offer was accepted! Here's what happens between now and closing, usually 30–45 days for a financed purchase.
Deliver your Due Diligence Fee and Earnest Money. The fee goes directly to the seller, and your Earnest Money is held in escrow. Both are credited toward your purchase at closing, and both need to arrive on time.
Schedule inspections right away. Any repair negotiations need to wrap up before your Due Diligence Period ends, so the sooner we have the report, the more time we have to work with.
Get insurance quotes early. Roof age or a home's location can affect coverage and cost, and it's better to learn that while you still have options. Your lender needs proof of coverage before approving your loan.
Appraisal. Your lender orders it, and ideally it's done during Due Diligence so you're protected from overpaying. The NC contract has no appraisal contingency unless we add an Appraisal Contingency Addendum.
Consider a survey. It's optional in NC but often recommended. It maps property lines and shows any encroachments, and we'd order it during Due Diligence.
Finalize your loan. You'll provide documents and go through underwriting with your lender.
Title search. NC is an attorney state, so your closing attorney checks for liens, judgments, unpaid taxes or other issues that could affect your ownership.
Clear to close. The magic words! Your loan is approved. You'll receive your Closing Disclosure at least three business days before closing, and we'll review it together.
Tip: Until closing, avoid changing jobs, making big purchases or opening new credit. Any of these can affect your loan approval, so check with your lender first.
The finish line
Closing Day
You've heard "clear to close" and closing is on the calendar. Here's what to expect.
Final walk-through. Shortly before closing, we'll confirm agreed-upon repairs were made and nothing new has come up.
Sign at your attorney's office. You'll sign your loan and closing documents with your closing attorney.
Bring a photo ID and send your funds. Your attorney will tell you how to send funds, usually by wire. Always call their office at a number you already know to confirm wiring instructions. Wire fraud is real, and I never want you to be a target.
Funding and recording. Once everything is signed and funded, your attorney records the deed with the Moore County Register of Deeds. Then the keys are yours. Celebrate!
Buyer FAQ
Your Questions, Answered
How much do I need to save for a down payment?
It depends on the loan type, but 5% is a good place to start, and many first-time buyers put down less than 20%. Some loans, like VA loans, don't require a down payment at all. A lender can show you how different down payment amounts change your monthly payment, including mortgage insurance.
How do I know if I qualify, and how much I can afford?
Contact a mortgage lender about pre-approval. They'll ask about your income and debts and tell you how much you can be approved for and what your payments would be.
What does the lender need from me?
Usually your last two tax returns, recent bank and credit card statements, and proof of your current pay. They'll also run a credit check. For a VA loan, you'll need your Certificate of Eligibility (COE), which your lender can often pull for you.
What's the difference between pre-qualified and pre-approved?
Pre-qualification is an estimate based only on what you share. Pre-approval means the lender has verified your income and debts and run a credit check.
Which mortgage option is right for me?
Your lender is the best person to advise you. Their products and requirements change from time to time, so they'll know which options fit your needs.
Do you have a lender I can talk to?
Yes! I work with several, including lenders who specialize in VA loans, and I'm happy to connect you. You're welcome to use your own, too.
When should I get pre-approved?
About 3–6 months before you'd like to move. If that's already passed, don't worry: pre-approvals take about 2–3 days. Just have yours before you start shopping. On PCS orders? Tell your lender early, since your report date will shape the timeline.
What is a VA loan?
One of the best benefits available to eligible veterans, active duty service members and some surviving spouses. VA loans are backed by the Department of Veterans Affairs and offered through private lenders.
How much do I need to put down?
In most cases, nothing. VA loans typically require no down payment and no PMI, even at 0% down, which can mean a lower monthly payment than other low-down-payment options.
What is the VA funding fee?
A one-time fee that can usually be rolled into your loan. The amount depends on your down payment and whether you've used your VA benefit before. Veterans receiving VA disability compensation are typically exempt.
Is the appraisal different with a VA loan?
A VA appraisal checks the home's value and that it meets the VA's minimum property requirements for things like safety and structural soundness. In North Carolina, VA loans also require a wood-destroying insect report.
Do I have to live in the home?
Yes, VA loans are for your primary residence. The good news: your benefit can be reused, and in some cases you can have more than one VA loan at a time.
If I'm putting 0% down, do I still need cash?
Usually, yes. You'll still need funds for your Due Diligence Fee, Earnest Money and inspections. The fee and deposit are credited toward your purchase at closing, and sellers can sometimes help with closing costs.
How do I know if I'm eligible?
Eligibility is based on your service history. Your lender can usually pull your Certificate of Eligibility for you, and I'm happy to connect you with lenders who work with VA buyers every day.
What should I do when I see a house online that I like?
Text me or send me a message in your Compass One dashboard! I'll pull the details, check the history and set up a showing. If you call the listing agent directly, remember they represent the seller, not you. Before we tour together, we'll sign a written buyer agreement that spells out what I'll do for you and how I'm paid.
Can you show me a house if it's not your listing?
Absolutely. As your buyer's agent, I can show you any home listed in our MLS, and I'll reach out to for-sale-by-owner sellers on your behalf, too.
How do we write an offer?
I'll pull comparable sales to help you land on a strong, fair price. Then we'll work through your terms: the Due Diligence Fee, Earnest Money, length of the Due Diligence Period and closing date. I'll write your offer and submit it to the seller's agent.
What if there are other offers on the house I love?
The seller's agent may ask for everyone's "highest and best." Price matters, but so do your terms, and I'll help you stay competitive.
What happens when my offer is accepted?
You'll deliver your Due Diligence Fee to the seller and your Earnest Money to escrow. I'll schedule inspections right away, and your lender will start processing your loan.
What does "under contract" mean?
You and the seller have both signed the contract and it's been delivered to both sides. Your Due Diligence Fee and Earnest Money then need to be delivered on time, or the seller can terminate.
What is the Due Diligence Fee?
A negotiated amount you pay directly to the seller for time to inspect the home and make sure it's right for you. It's credited toward your purchase price at closing. If you walk away, it's generally non-refundable.
What is Earnest Money?
A good-faith deposit held in escrow and credited at closing. If you terminate before your Due Diligence Period ends, it's returned to you. After that, it's generally at risk unless the seller breaches. A larger deposit can strengthen your offer.
What if I want to back out?
You can terminate for any reason before your Due Diligence Period ends. You'll lose your Due Diligence Fee, but your Earnest Money is returned. After Due Diligence ends, backing out generally means losing your Earnest Money too, unless the seller breaches the contract.
Do I need an inspection?
I recommend one on every home, even new construction. A few hundred dollars for peace of mind on one of the biggest purchases you'll make is well worth it.
How much are inspections?
It depends on the home's size and any add-ons. In Moore County, common add-ons include a termite report, septic and well inspections, and radon testing. A standard inspection typically runs several hundred dollars, and I'm happy to share local inspectors I trust.
What if my loan doesn't get approved?
If you've been upfront with your lender, it's unlikely. Avoid new debt, big purchases or job changes until closing. The NC contract doesn't include a financing contingency, so if there's any concern about your loan, you need to know before Due Diligence ends.
When can I start moving?
Once the deed is recorded and you have the keys! Unless you and the seller agree otherwise in writing, possession transfers at closing, so the home should be vacant and ready for you.
here for you!
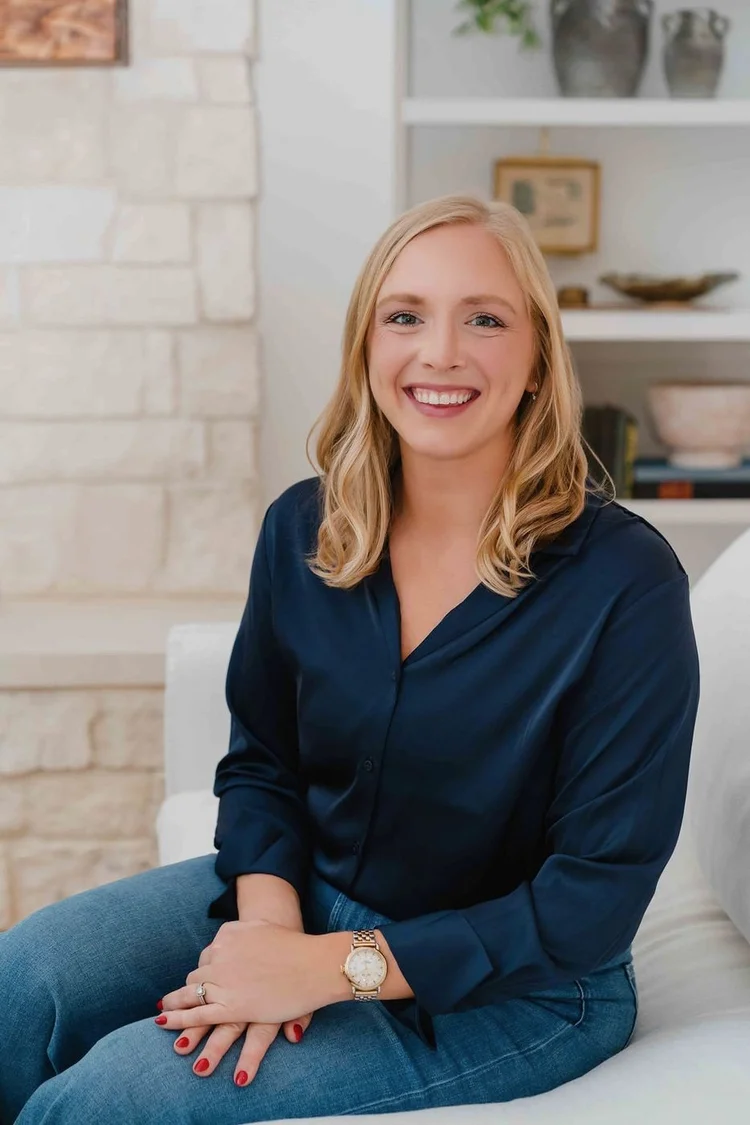
Your buyer's agent in Moore County
Let's find home
Michigan was home first, but college brought me to the Carolinas and I never wanted to leave. When the military brought my husband, Max, and me to Southern Pines, what we thought was a temporary stop became the destination. Every move has taught me the house is only part of the decision. The neighborhood, the commute and the lifestyle matter just as much.
Before real estate, I spent eight years in public health and research, including time with the VA, where accuracy and deadlines were nonnegotiable. I bring that same discipline to every contract and closing, with The Foundry Group and Compass behind you.
Lex Fowler, REALTOR® · The Foundry Group at Compass · @lexfowler_realestate
Next up
Selling before you buy?
How to prep, price and show your home, and what to expect at closing.